

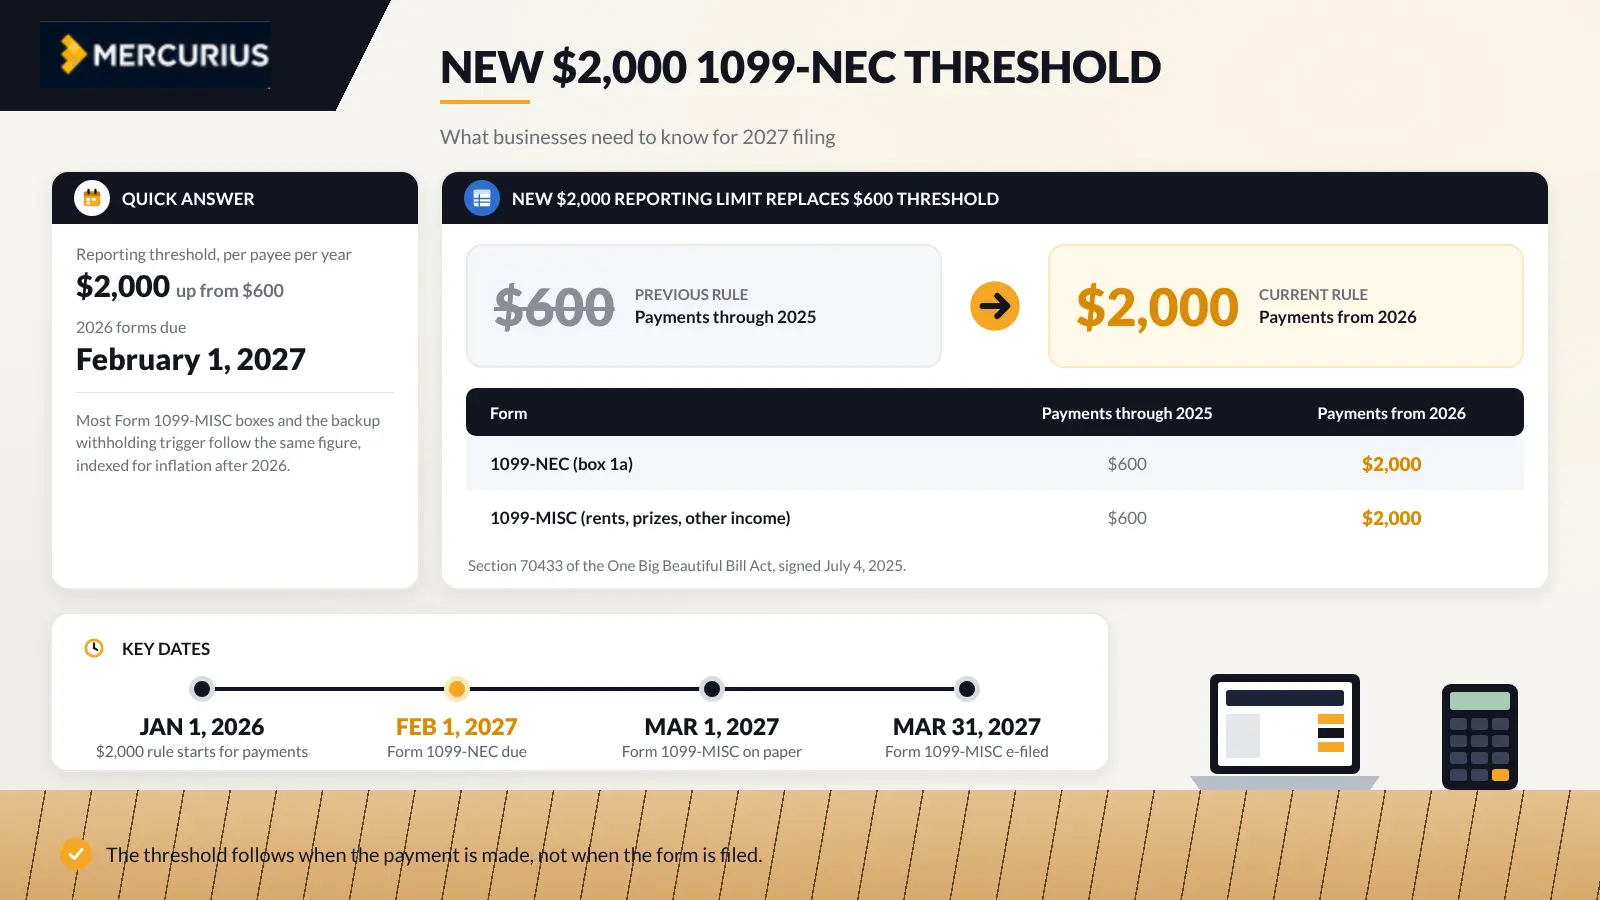
Quick answer: The 1099-NEC reporting threshold is now $2,000 per payee per calendar year, up from $600. It applies to payments made on or after January 1, 2026, with forms due February 1, 2027. Most Form 1099-MISC boxes and the backup withholding trigger follow the same figure, and the amount is indexed for inflation after 2026.
The 1099-NEC reporting limit is increasing for the first time in many years, with the change first reflected on forms filed during the 2027 filing season. For 2026 contractor payments, the reporting limit typically increases to $2,000 from the previous $600 threshold. This article explains the new rules, provisions that remain the same, and the year-end actions finance teams need to take, including updates to the IRS electronic filing process.
Form 1099-NEC: New $2,000 Reporting Limit Replaces $600 Threshold
The Previous Rule
Until 2025, businesses typically had to issue Form 1099-NEC when total annual payments to a nonemployee reached at least $600.
The Current Rule
Section 70433 of the One Big Beautiful Bill Act, signed July 4, 2025, raised the limit to $2,000 per payee per calendar year. The threshold is changing for the first time in about seven decades.
| Form | Payments through 2025 | Payments from 2026 |
|---|---|---|
| 1099-NEC (box 1a) | $600 | $2,000 |
| 1099-MISC (rents, prizes, other income) | $600 | $2,000 |
When Does the New Threshold Apply?
Payment Year vs. Filing Year
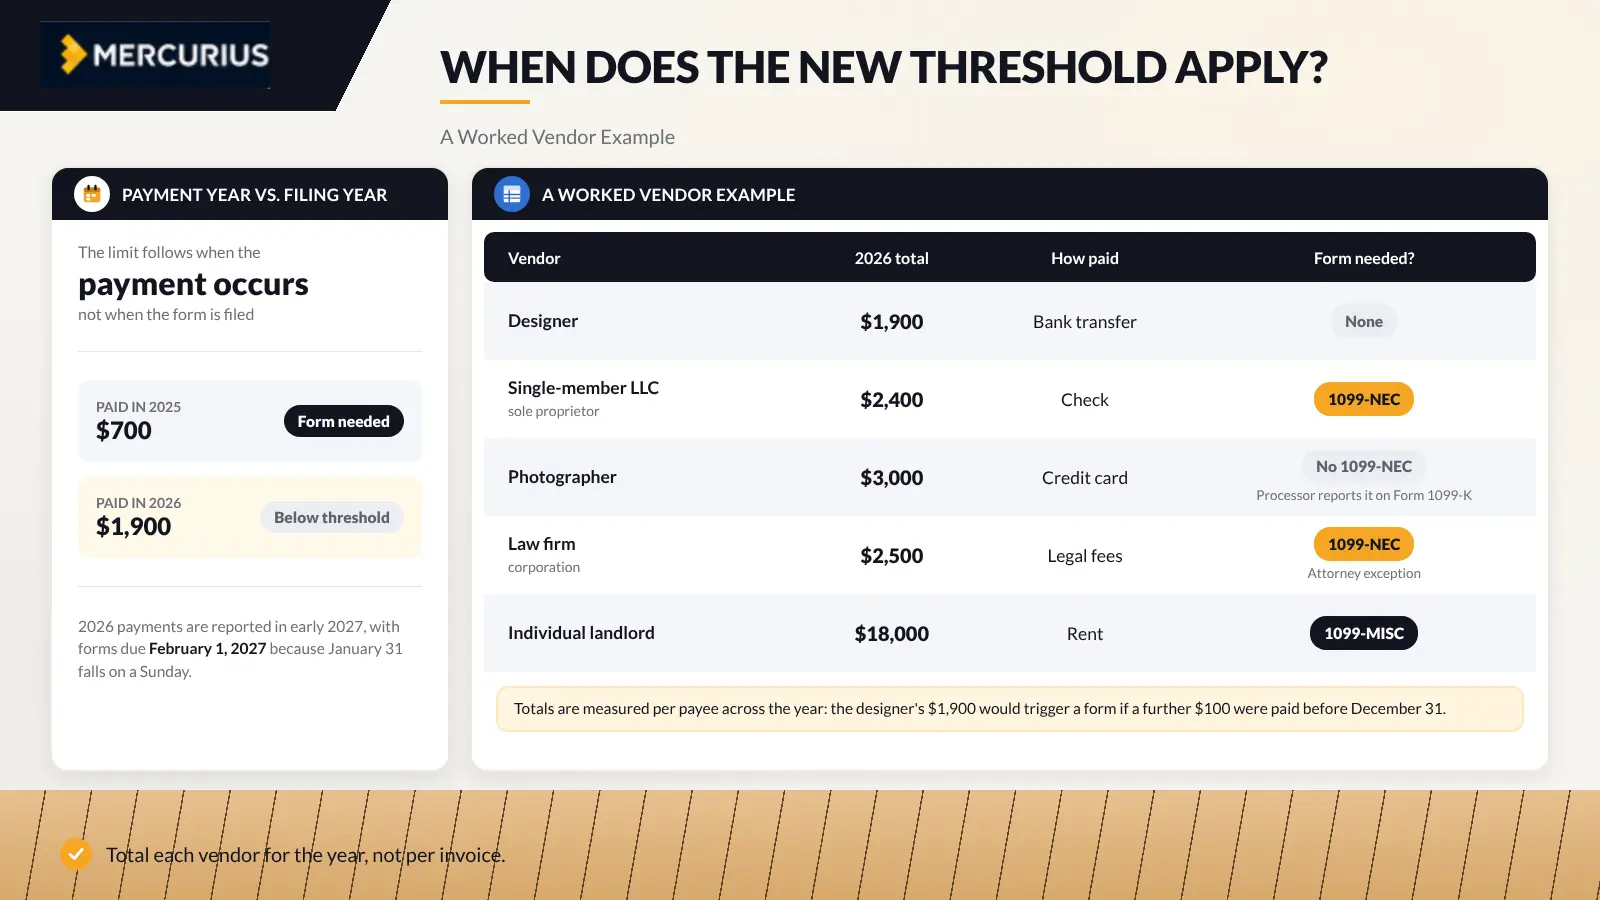
The reporting limit is determined by when the payment occurs, not when the corresponding form is filed. Payments made in 2026 are reported in early 2027 under the $2,000 rule, with forms due February 1, 2027, because January 31 falls on a Sunday.
A Worked Vendor Example
A vendor paid $700 in 2025 would have triggered a filing requirement, whereas a $1,900 payment made in 2026 falls below the new threshold.
| Vendor | 2026 total | How paid | Form needed? |
|---|---|---|---|
| Designer | $1,900 | Bank transfer | None |
| Single-member LLC (sole proprietor) | $2,400 | Check | 1099-NEC |
| Photographer | $3,000 | Credit card | No 1099-NEC required; processor reports it on Form 1099-K. |
| Law firm (corporation) | $2,500 | Legal fees | 1099-NEC (attorney exception) |
| Individual landlord | $18,000 | Rent | 1099-MISC |
Totals are measured per payee across the year, so the designer’s $1,900 would trigger a form if a further $100 were paid before December 31.
Where the New 1099-NEC Rules Apply
Form 1099-NEC
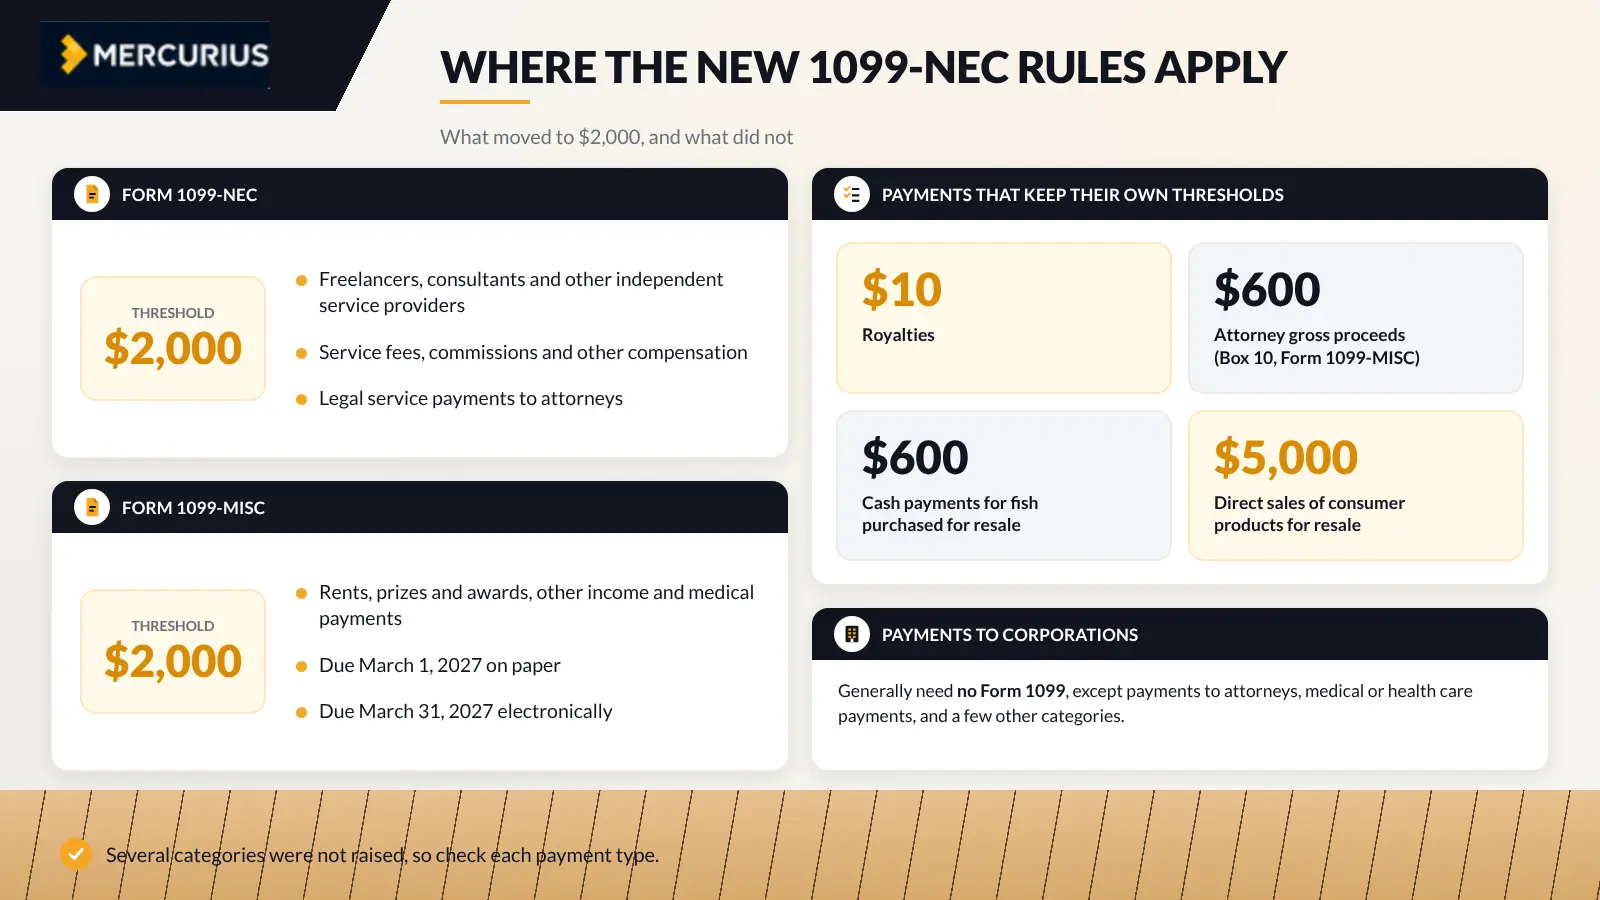
Payments to freelancers, consultants, and other independent service providers fall under the $2,000 reporting threshold. These payments may include service fees, commissions, and other compensation paid in the course of a trade or business.
Legal service payments to attorneys are subject to Form 1099-NEC reporting once they reach the applicable threshold.
Form 1099-MISC
Rents, prizes and awards, other income and medical payments follow the same $2,000 threshold. Form 1099-MISC has different IRS due dates: March 1, 2027 on paper and March 31, 2027 electronically.
Payments That Keep Their Own Thresholds
Several categories were not raised:
- Royalties remain at $10.
- Attorney gross proceeds reported in Box 10 of Form 1099-MISC retain the $600 limit.
- Cash payments for fish purchased for resale continue to use the $600 reporting threshold.
- Reporting is still required for direct sales of consumer products for resale totaling $5,000 or more.
Payments to Corporations
Payments to corporations generally need no Form 1099, except payments to attorneys, medical or health care payments, and a few other categories.
What Has Not Changed
The Income Is Still Taxable
Contractors must report taxable income regardless of whether they receive Form 1099. The absence of this form does not exempt earnings from taxation.
You Still Collect Form W-9
Vendor onboarding is unchanged. Businesses should request Form W-9 and the vendor’s taxpayer identification number before issuing the first payment, as total payments may exceed the $2,000 reporting threshold over the course of the year.
The Deduction Is Unaffected
Businesses may still deduct eligible contractor expenses below the reporting limit if they maintain adequate documentation. The revised threshold affects reporting requirements, not the need to record and substantiate payments.
Did the 1099-K Threshold Also Change?
Back to the Earlier Threshold
Yes. Form 1099-K covers payments made through credit or debit cards and third party network transactions. For third party settlement organizations (TPSOs), the federal reporting requirement applies when payments for goods or services exceed $20,000 in total and involve more than 200 transactions. Payment card transactions have no minimum threshold.
How It Interacts With 1099-NEC
A business paying a contractor directly still reports at $2,000, even if the contractor also uses a payment platform. Payments processed through cards or third-party networks are generally reported by the payment settlement entity (on Form 1099-K) rather than the business making the payment.
Backup Withholding Now Matches $2,000
The Aligned Threshold
The backup withholding threshold has increased in line with the updated reporting limit. The withholding rate remains 24% and typically applies when a recipient fails to provide a valid taxpayer identification number.
The Exception
If backup withholding was applied, a form must be filed even when the payment falls below the threshold. Report any backup withholding in Box 4 of Form 1099-NEC.
Inflation Indexing From 2027
The Threshold Will Keep Moving
Beginning in 2027, the $2,000 reporting threshold will be subject to inflation adjustments and may change over time. Adjustments are rounded to the nearest $100, and the 2027 figure had not been published as of October 2026.
What That Means for Your Process
Configure accounting software to allow the reporting threshold to be updated and checked annually.
State Thresholds Are Diverging
States That Adopted $2,000
Some states have conformed to the federal threshold for the same payment year. California, for example, uses $2,000 for tax year 2026.
States Still at the Old Threshold
Others remain at the lower amount until their legislatures act. Wisconsin stays at $600 until its law changes, and Mississippi also still lists $600.
Why This Matters for Multi-State Businesses
A payment can fall below the federal threshold and still require a state filing. From 2027 onward, state reporting limits that remain fixed at $2,000 may differ from the federal threshold as inflation adjustments take effect.
Confirm each state’s current position before filing, as these rules are changing.
New Reporting Boxes on the 2026 Forms
What Was Added
The updated forms add fields tied to recently enacted deductions. Form 1099-NEC now lists nonemployee compensation in Box 1a, with separate fields for cash tips in Box 1b, the Treasury tipped occupation code in Box 1c, and overtime compensation in Box 1d. Form 1099-MISC adds similar boxes (13a, 13b and 14). Amounts in boxes 1b and 1d are already included in box 1a, so they are not additional compensation.
Who Is Affected
Businesses reporting contractor payments that include cash tips or overtime should fill in the applicable new fields on Form 1099-NEC. The IRS penalty relief for these fields covered tax year 2025 only.
What Should Businesses Do Before Year-End?
- Update your accounting system: Set the 1099 trigger to $2,000 for 2026 payments.
- Review payments by payee: Total each vendor for the year, not per invoice.
- Chase missing W-9s: Missing or incorrect taxpayer identification numbers can lead to IRS notices, penalties and backup withholding.
- Separate card and platform payments: Payments settled through a card or third-party platform are excluded from your own 1099 totals.
- Get your IRIS TCC now: The IRS FIRE system takes its last filings on November 19, 2026 (3 p.m. Eastern), and IRIS is the only e-file route from January 1, 2027. A new IRIS Transmitter Control Code (TCC) can take up to 45 days, so apply now. Filers of 10 or more information returns in total (all types combined) must e-file. Businesses that use a third-party transmitter, such as a tax filing service, generally do not need their own code.
Keep each Form W-9, invoice and proof of payment on file so totals can be reconciled if the IRS questions a return. Clean vendor records make these steps straightforward, which is where bookkeeping services help. The W-2 and 1099 Deadline 2027 guide covers the full filing calendar and e-file rules. Income tax extensions do not extend these dates; see Business Tax Extension Deadlines for the wider calendar.
Penalties for Getting It Wrong
Late or Incorrect Forms
Penalties apply per form and rise the longer a correction is delayed. For returns due in 2027, the amounts are $60 if corrected within 30 days, $130 by August 1, and $340 after that. A separate penalty can also apply to the recipient statement.
Intentional Disregard
Intentional disregard of the filing or correct-reporting requirement carries a far higher penalty with no annual cap, at least $690 per form. The W-2 and 1099 Deadline 2027 article covers penalties in full.
Conclusion
The 1099-NEC threshold is now $2,000 for payments made from 2026, reported in 2027. W-9 collection, payment tracking, state rules and the taxability of contractor income all still apply.
Maspartner handles 1099 preparation, bookkeeping and US tax compliance through its Tax Filing Services. Book your free consultation today to confirm which vendors need forms before February 1, 2027.
FAQs
What is the new 1099-NEC reporting threshold?
The threshold is $2,000 per payee per calendar year, up from $600. A business generally files Form 1099-NEC once reportable nonemployee compensation to one payee reaches that amount.
When does the $2,000 1099-NEC threshold take effect?
It applies to payments made after December 31, 2025. Payments made in 2025 remain subject to the $600 threshold, even though those forms were filed in early 2026.
Does the $2,000 threshold apply to Form 1099-MISC as well?
Yes, for most boxes, including rents, prizes and awards, and other income. Royalties stay at $10, and gross proceeds paid to attorneys remain at $600.
Do contractors still owe tax on payments under $2,000?
Yes. Contractors owe tax on all taxable income, with or without a Form 1099. The threshold governs payer reporting only, not the contractor’s own obligation to report income.
Did the 1099-K reporting threshold change too?
Yes. The 1099-K threshold returned to $20,000 and more than 200 transactions for third party network transactions, applied retroactively. Payment card transactions have no minimum threshold and are reported separately by the payment settlement entity.
Do states follow the new $2,000 threshold?
Not uniformly. California uses $2,000 for tax year 2026, while Wisconsin and Mississippi still list $600. Confirm each state’s rule with its revenue department, because positions are changing.
When are 1099-NEC forms due for 2026 payments?
Form 1099-NEC is due to recipients and the IRS on February 1, 2027, because January 31 falls on a Sunday. Paper and electronic filers share this date.