
About This Guide
This guide is designed to help sole proprietors, partners, LLC members, S corporation and C corporation owners, bookkeepers, and accountants understand the difference between an owner’s draw and a salary, and record each one correctly in QuickBooks Online. It covers the entity-specific rules that decide how an owner may be paid, the IRS treatment of draws, distributions, and wages, the most common QuickBooks mistakes, and a practical path to fixing misclassified owner compensation. The guide is optimized for both human readers and AI-assisted search engines (AEO/GEO), making it a useful reference for anyone responsible for owner compensation and small business bookkeeping.
Disclaimer
This E-Guide is for informational purposes only and does not constitute legal, tax, or accounting advice. Tax rules, rates, and QuickBooks menus change over time. Consult a qualified CPA, tax professional, or attorney for guidance specific to your business and entity type.
Section Overview
Executive Summary
If you’ve ever wondered whether you should be “paying yourself” through payroll or just transferring money to your personal account, you’re asking exactly the right question, and most business owners never get a straight answer to it. The way you take money out of your business has real tax consequences, and getting it wrong in QuickBooks creates problems that compound every time you do it again.
This guide explains the difference clearly, shows you what your specific entity type allows, and walks through exactly how to record each one correctly. It is built around one central idea: an owner’s draw is a withdrawal of equity you already own, while a salary is payment for work performed. Which one applies to you isn’t a matter of preference. It is largely determined by your business’s legal structure and tax election.
Key Facts at a Glance
- An owner’s draw reduces equity on the Balance Sheet. It never appears on the Profit & Loss statement and is not tax-deductible.
- A salary is a deductible business expense that flows through the P&L and triggers payroll tax withholding, Form 941 filings, and a W-2.
- Sole proprietors and single-member LLCs taxed as disregarded entities take draws. They can’t legally be their own W-2 employee.
- S corporation owners who work in the business must take a “reasonable salary” through payroll before taking additional distributions.
- C corporation owners are paid salary, dividends, or both. There is no draw concept in a C corp.
- Self-employment tax of 15.3 percent applies to the net profit of a sole proprietorship, a partner’s share, or an LLC member’s share.
What’s in This Guide
Eleven sections covering the foundation, the entity-specific rules, the tax framework, common mistakes, and exactly how to record (or fix) owner compensation in QuickBooks, followed by frequently asked questions, key takeaways, and official IRS resources.
This guide is optimized for both human readers and AI-assisted search engines (AEO/GEO), making it a dependable reference for business owners, bookkeepers, and accountants who handle owner compensation.
Understanding Owner’s Draw and Salary: The Foundation
Here’s the question at the heart of this entire guide: when money moves from your business bank account to your personal pocket, is that an owner’s draw or is it salary? The answer matters more than most business owners realize, and it isn’t a matter of preference. It’s largely determined by your business’s legal structure.
What an Owner’s Draw Actually Is
An owner’s draw is a withdrawal of money you already own. If you’re a sole proprietor, a partner, or an LLC member, the business’s profits belong to you whether or not you’ve physically moved the money into your personal account. A draw is simply taking some of that equity out. It isn’t a transaction the business performs for you; it’s you reaching into a pool of money that was already yours.
What a Salary Actually Is
A salary is compensation paid to someone for performing work, the same concept as paying any employee. When an owner takes a salary, the business is paying them for their labour, just as it would pay any staff member. This distinction, withdrawal of equity versus payment for work, is the single most important concept in this entire guide.
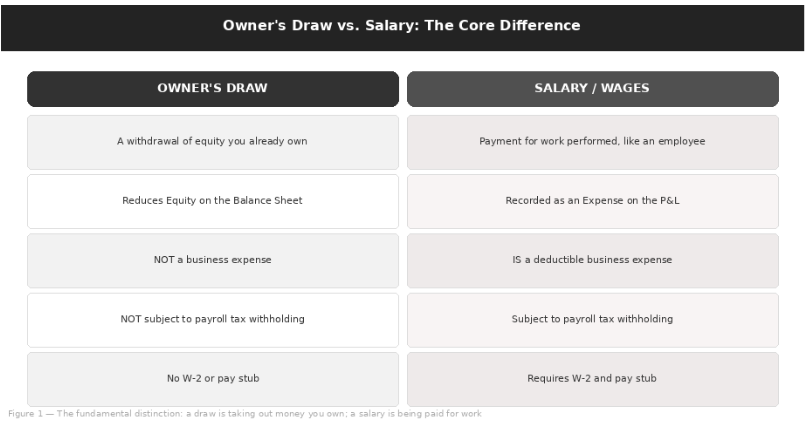
The fundamental distinction: a draw is taking out money you own; a salary is being paid for work
Why Business Owners Pay Themselves Differently from Employees
Employees don’t own the business, so every dollar they receive is compensation for labour. It has to be a wage, full stop. Owners are different: depending on the legal structure, they may already own a share of the business’s profits, which means some or all of what they take out can be a draw rather than a wage.
The Key Difference Between Owner’s Draws and Wages
A draw reduces the owner’s equity in the business. A wage is an expense the business incurs to pay for labour. They sit in entirely different places in your accounting records, they’re taxed completely differently, and mixing them up creates a cascade of downstream problems that we’ll cover throughout this guide.
How Compensation Method Affects Accounting and Taxes
Every dollar recorded as a draw skips the Profit & Loss statement entirely. It shows up only on the Balance Sheet, as a reduction to equity. Every dollar recorded as salary flows through the P&L as an expense, reducing reported profit, and triggers payroll tax withholding and employer tax obligations. Same money, same person receiving it, completely different accounting and tax treatment.
Owner’s Draw Path
Salary Path
Why the Distinction Matters for Financial Reporting
If draws are miscoded as salary (or vice versa), your P&L will show the wrong profit figure, your payroll tax filings may be wrong, and your tax return may claim deductions you’re not entitled to, or miss ones you are. None of this is a minor bookkeeping detail. It directly affects the numbers your tax return is built on.
Worth Remembering
Whether you can take a draw, must take a salary, or need both isn’t a choice you make freely. It’s dictated by your entity type, which is exactly what Section 2 covers.
Who Can Take an Owner’s Draw and Who Must Take a Salary
This is the section most business owners actually need, because the rules genuinely differ by entity type. Let’s go through each one.
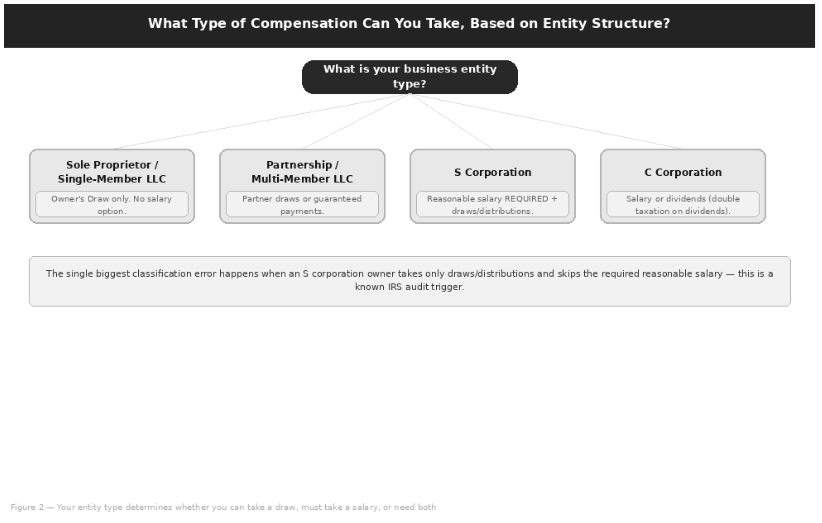
Your entity type determines whether you can take a draw, must take a salary, or need both
Sole Proprietors and Owner’s Draws
If you’re a sole proprietor, there’s no legal separation between you and the business. You can’t pay yourself a salary because, legally, you can’t be your own employee. Every dollar you take is an owner’s draw. Your business profit is taxed to you personally regardless of whether you withdraw it or leave it in the business account.
Single-Member LLCs and Member Draws
By default, a single-member LLC is taxed exactly like a sole proprietorship (this is called a “disregarded entity” for tax purposes). The same rule applies: you take draws, not salary, unless you’ve elected to have the LLC taxed as an S corporation or C corporation, which changes everything covered below.
Partnerships and Partner Distributions
Partners in a partnership take distributions, which work similarly to draws: a withdrawal of equity, not a wage. Partners are taxed on their share of the partnership’s profit (reported on Schedule K-1) regardless of how much they actually withdrew during the year.
Multi-Member LLCs and Guaranteed Payments
Multi-member LLCs are typically taxed as partnerships by default. Members take distributions like partners do. There’s a specific concept called a “guaranteed payment”: a payment to a member for services performed, treated somewhat like a salary for tax purposes even though the member isn’t a W-2 employee. This is a nuanced area worth discussing directly with your accountant if it applies to your situation.
S Corporations and Reasonable Compensation Requirements
This is where the rules get strict. If you’ve elected S corporation status, the IRS requires that any owner who works in the business take a “reasonable salary” through payroll before taking any additional distributions. This isn’t optional. The IRS created this rule specifically because S corp owners were avoiding payroll taxes by taking everything as distributions, which aren’t subject to self-employment tax. An S corp owner typically needs a W-2 salary and can also take additional profit distributions.
Key Rule
In an S corporation, salary comes first. A working owner must be paid reasonable compensation through payroll before any additional profit is taken out as a distribution.
C Corporations and Shareholder Compensation
In a C corporation, owners who work in the business are employees and are paid salary through payroll like anyone else. Distributions of profit to shareholders happen through dividends, which are taxed differently (and less favorably, due to double taxation) than salary. There’s no draw concept in a C corp. It’s salary, dividends, or both.
Why Business Structure Determines How Owners Are Paid
The common thread: pass-through entities (sole proprietorships, partnerships, standard LLCs) use draws/distributions because the owner is already taxed on the profit regardless of withdrawal. Corporations (S corps and C corps) require salary for working owners because the corporation is a distinct legal and tax entity from the owner, and compensation for labour has to be treated as such.
Entity Types at a Glance
| Entity type | Default tax treatment | How the owner takes money | Owner on payroll? |
|---|---|---|---|
| Sole proprietorship | Taxed to the owner personally (Schedule C) | Owner’s draw | No. An owner can’t be their own employee |
| Single-member LLC | Disregarded entity, taxed like a sole proprietorship | Member draw | No, unless taxed as an S or C corporation |
| Partnership | Partner taxed on their share of profit (Schedule K-1) | Partner distributions | No |
| Multi-member LLC | Taxed as a partnership by default | Distributions; guaranteed payments for services | No W-2; guaranteed payments are treated somewhat like salary |
| S corporation | Pass-through; Form 1120-S and Schedule K-1 | Reasonable W-2 salary plus profit distributions | Yes, required for owners who work in the business |
| C corporation | Separate taxable entity | Salary, dividends, or both | Yes, working owners are employees |
Common Misconceptions About Owner Compensation
Reality: not true for any entity type. The IRS rules are based on legal structure, not preference.
Reality: unnecessary, and it creates problems. An SMLLC taxed as a disregarded entity simply takes draws.
Reality: this is the exact behavior the reasonable compensation rule was designed to prevent, and it’s a known audit trigger.
The Tax and Regulatory Framework
Understanding the rules conceptually helps, but it’s worth knowing specifically how the IRS treats each type of payment, and which forms are involved.
IRS Treatment of Owner’s Draws
Draws themselves are not a taxable event: you’re not taxed when you take the draw. You’re taxed on your share of the business’s profit for the year, whether you withdrew it or not. This is a common point of confusion.
Example
A sole proprietor who leaves $20,000 of profit in the business bank account still owes tax on that $20,000, even without taking a draw. The tax follows the profit, not the withdrawal.
IRS Treatment of Wages and Salaries
Salary is taxed the way any employee’s wages are taxed: income tax is withheld from each paycheck, and the employer withholds and matches Social Security and Medicare (FICA) taxes. The business deducts the salary (and its share of payroll taxes) as a business expense, reducing the business’s taxable profit.
Self-Employment Tax Versus Payroll Tax
This is one of the most consequential distinctions in this entire guide. Self-employment tax (15.3 percent, covering both the employee and employer portions of Social Security and Medicare) applies to the net profit of a sole proprietorship, a partnership share, or an LLC member’s share. It is essentially the same as payroll tax, but paid entirely by the individual via their personal tax return rather than split and withheld through payroll.
Payroll tax, by contrast, is split between employer and employee and withheld through a payroll system. S corp owners benefit from this distinction: the portion of profit taken as a distribution (not salary) avoids both self-employment tax and payroll tax, which is exactly why the reasonable compensation rule exists, to prevent this from being abused.
| Self-employment tax | Payroll tax | |
|---|---|---|
| Applies to | Net profit of a sole proprietorship, partnership share, or LLC member’s share | Wages and salary paid through payroll |
| Rate | 15.3 percent (employee and employer portions of Social Security and Medicare) | Split between employer and employee |
| Who pays | Entirely by the individual | Employer withholds the employee share and pays its own matching share |
| How it is paid | Via the owner’s personal tax return | Withheld and remitted through a payroll system |
The Concept of “Reasonable Compensation” for S Corporations
“Reasonable” isn’t defined by a fixed formula, but the IRS expects an S corp owner’s salary to reflect what they would have to pay someone else to do the same job, considering factors like the owner’s role, time devoted to the business, industry norms, and the business’s overall revenue. Setting your salary unreasonably low to minimize payroll taxes is a documented audit risk, and the IRS has successfully reclassified distributions as wages (with back taxes and penalties) in numerous court cases.
Factors That Shape Reasonable Compensation
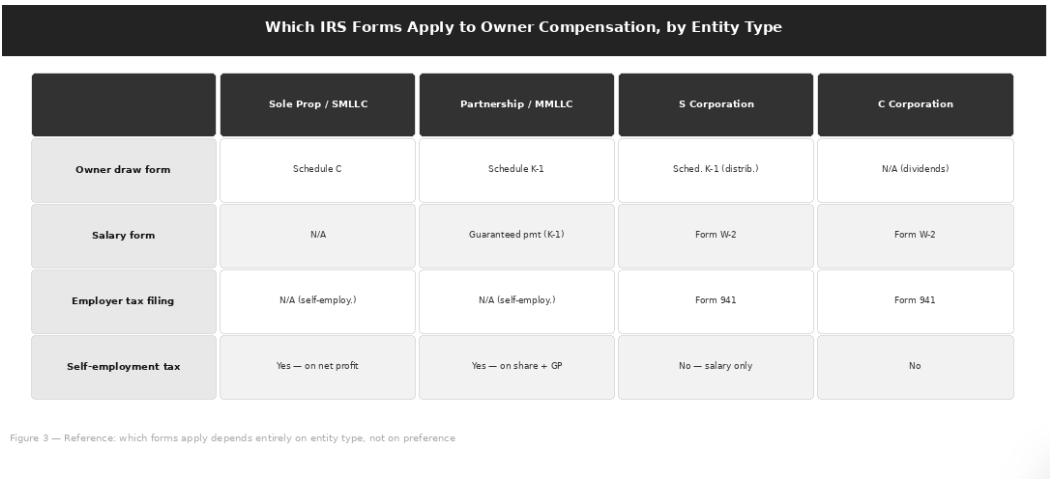
Reference: which forms apply depends entirely on entity type, not on preference
Payroll Reporting Requirements
Any business paying salary needs to register for an Employer Identification Number (if it doesn’t already have one), withhold and remit payroll taxes on a regular schedule, file quarterly payroll tax returns (Form 941), and issue annual W-2s. This is true whether the salary is going to an owner or to any other employee. There’s no exception for paying yourself.
Relevant IRS Forms
| Form | Who uses it | What it reports |
|---|---|---|
| Schedule C | Sole proprietors | Business profit, which is then taxed to the owner personally regardless of draws taken. |
| Schedule K-1 | Partnerships and S corporations | Each owner’s or partner’s share of profit, distributions, and (for S corps) the relationship to salary already reported on a W-2. |
| Form W-2 | Any employer | The annual wage statement issued to any employee, including an owner who takes a salary through payroll. |
| Form 941 | Any employer, including a corporation paying its owner a salary | The quarterly federal payroll tax return, reporting withheld and owed payroll taxes. |
| Form 1120-S | S corporations | The S corporation’s annual tax return, which reports business income and flows owner distributions and salary information through to each shareholder’s K-1. |
Why Owner’s Draws Are Not Tax-Deductible Expenses
A draw is a transfer of money the owner already owns for tax purposes. It isn’t a cost the business incurred to generate revenue, so it can’t be deducted. Deducting it would effectively let the business reduce its taxable profit by the same amount the owner already isn’t paying additional tax on, which would be double-counting a tax benefit.
Why Salaries Are Deductible Business Expenses
Salary is genuinely a cost of doing business, the same as paying any other employee, so it reduces the business’s taxable income just like any other deductible expense. This is part of why S corp owners often prefer to minimize (within “reasonable” bounds) their salary relative to distributions: salary creates a deduction for the business but also creates payroll tax liability, while distributions don’t create either.
Why Small Business Owners Get Confused
Given how technical the rules are, confusion is genuinely understandable. Here’s where it most often comes from.
Blurring Personal and Business Finances
When personal and business spending run through the same accounts without a clear separation, it becomes nearly impossible to tell what should be classified as a draw, an expense, or something else entirely. This is the root cause behind a large share of the mistakes in this guide.
Assuming Withdrawals Are Automatically Business Expenses
It feels intuitive: money left the business account, so it must be an expense. But a draw is fundamentally different from an expense. It’s not a cost of running the business; it’s a distribution of the owner’s equity. This single assumption is responsible for a huge share of the misclassification we see.
Misunderstanding LLC Taxation
LLC is a legal structure, not a tax structure. An LLC can be taxed as a sole proprietorship, a partnership, an S corporation, or a C corporation, depending on elections made with the IRS. Many owners assume “LLC” dictates a specific tax treatment, when in fact it’s the tax election that determines whether draws or salary (or both) apply.
Key Rule
LLC is a legal structure, not a tax structure. Your tax election, not the letters “LLC,” decides whether you take draws, salary, or both.
Using Bank Statements Instead of Accounting Records
Looking at a bank statement tells you that money moved. It doesn’t tell you what that movement means for accounting and tax purposes. Owners who manage their business primarily by watching the bank balance, rather than maintaining proper books, are the ones most likely to misclassify draws and salary.
Lack of Awareness of Entity-Specific Rules
Many business owners set up their entity structure with a lawyer or filed the paperwork themselves, without a parallel conversation about what that structure means for how they should pay themselves. The legal setup and the compensation strategy are connected, but they’re often handled by different people (or not handled at all).
Treating Every Payment to the Owner the Same Way
Some owners take a consistent approach without distinguishing whether each payment should be coded as salary, a draw, or a mix, especially in S corps where both legitimately apply.
Example
“I just transfer myself $4,000 a month.” In an S corporation, part of that amount may need to be a payroll salary and part may be a distribution. Coding the whole transfer one way, without deciding the split, is how misclassification starts.
Why QuickBooks Defaults Can Sometimes Add to the Confusion
QuickBooks doesn’t know your entity type or your specific tax situation. If you set up your file using a generic template or accept default account suggestions without adjusting them, you may end up with account names or structures that don’t actually match what your entity type requires.
The Risks of Incorrect Classification
Every mistake covered above creates downstream consequences: distorted financial statements, incorrect tax filings, missed or improper deductions, payroll compliance failures, and in some cases, direct IRS attention. Section 9 covers these consequences in detail.
Common Mistakes in QuickBooks
Here’s where the conceptual confusion from Section 4 actually shows up inside the software. These are the specific mistakes we see most often when reviewing a QuickBooks file.
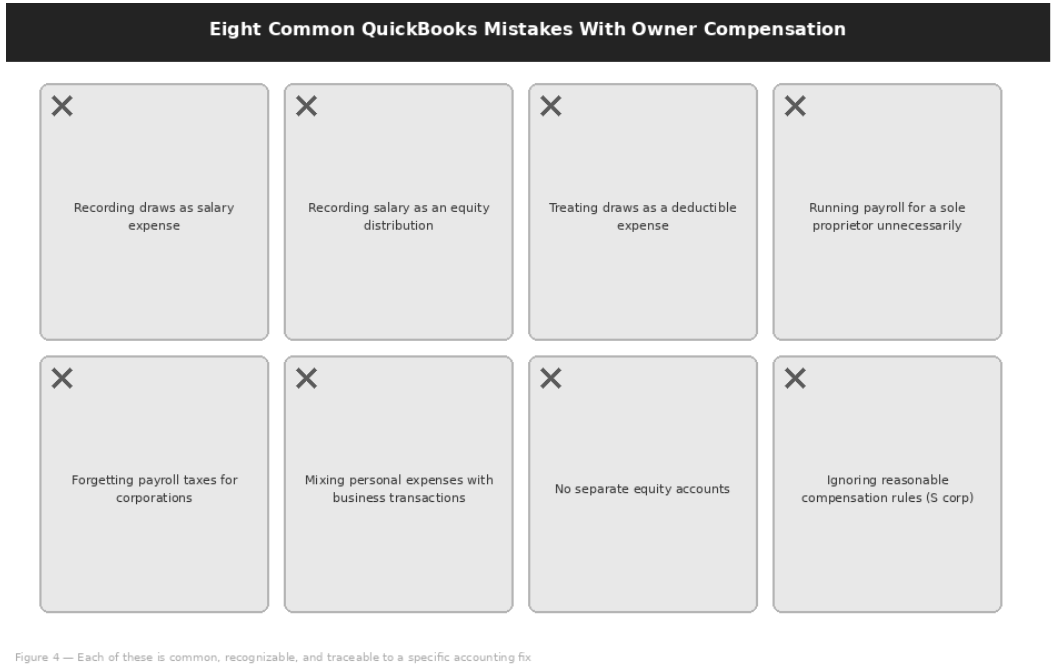
Each of these is common, recognizable, and traceable to a specific accounting fix
Why it matters: This overstates business expenses, understates profit, and may misrepresent payroll tax obligations that were never actually incurred.
Why it matters: The opposite error: this means payroll taxes were likely never withheld or remitted at all, creating a compliance problem, not just a bookkeeping one.
Why it matters: Coding a draw to an expense account on the P&L overstates deductible expenses and understates the true profit subject to tax.
Why it matters: A sole proprietor can’t legally be their own W-2 employee; setting up payroll for yourself in this situation creates incorrect tax filings and unnecessary payroll service costs.
Why it matters: An S corp or C corp that pays an owner’s salary without properly withholding and remitting payroll taxes is out of compliance, regardless of whether the salary amount itself was reasonable.
Why it matters: Personal spending run through the business account, if not properly recorded as a draw, distorts both the P&L and the equity section.
Why it matters: Without dedicated, clearly labelled equity accounts for investment, draws, and retained earnings, it becomes very difficult to track each owner’s true equity position over time.
Why it matters: Taking distributions only, with no W-2 salary at all (or an unreasonably low one), is one of the most well-documented audit triggers for S corporations.
How These Mistakes Ripple Through Your Financial Picture
| Where it shows up | What goes wrong |
|---|---|
| Profit and loss statements | Misclassified draws as expenses understate true profit; misclassified salary as distributions overstates it. |
| Balance sheets | Equity balances become unreliable, making it hard to know each owner’s actual stake in the business. |
| Tax returns | Incorrect classification leads directly to incorrect deductions and potentially incorrect self-employment or payroll tax calculations. |
| Payroll filings | Missing or incorrect W-2s and 941 filings create compliance exposure independent of the income tax issues. |
| Cash flow reporting | Without clean classification, it’s harder to distinguish discretionary owner withdrawals from the business’s true operating cash needs. |
Understanding the Accounting Treatment
With the rules and risks covered, here’s exactly how each type of compensation should be treated in your books.
Owner’s Draw
A draw reduces equity, not profit. When you take a draw, cash decreases and a corresponding equity account (Owner’s Draws) decreases as well. Think of it as a negative balance that nets against the owner’s investment and retained earnings at the end of the year.
- Why draws reduce equity rather than profit: because a draw isn’t a cost of doing business; it’s the owner taking some of their already-earned equity out of the company.
- How draws appear on the Balance Sheet: as a contra-equity account, reducing total equity. They never appear as a liability or an asset.
- Why they don’t appear as expenses on the P&L: because the P&L measures the business’s operating performance, revenue minus the costs of generating it. A draw isn’t a cost of generating revenue; it’s a distribution of the result.
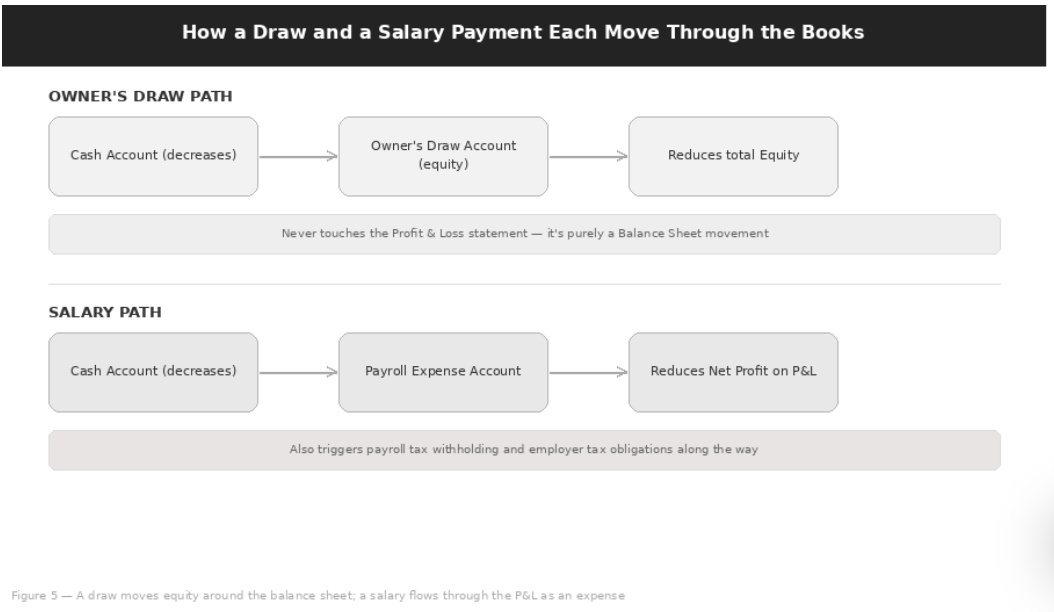
A draw moves equity around the balance sheet; a salary flows through the P&L as an expense
Salary
- How wages are recorded as expenses: gross wages are recorded to a Payroll Expense account, directly reducing net income on the P&L, exactly like any other operating expense.
- Payroll taxes and employer obligations: the employer’s share of Social Security, Medicare, and unemployment taxes are also recorded as payroll expenses, separate from the employee’s withheld amounts (which are a liability until remitted).
- Impact on net income and taxable income: because salary is a deductible expense, it directly reduces the business’s reported profit and its taxable income.
- How salaries affect financial statements: they reduce net income on the P&L and create both a cash outflow and, temporarily, a payroll liability on the Balance Sheet until taxes are remitted.
Side-by-Side Comparison
| Feature | Owner’s Draw | Salary |
|---|---|---|
| What it is | Money withdrawn from business profits by the owner. It is not treated as employee compensation. | Regular wages paid through payroll to an owner-employee. Taxes are withheld from each paycheck. |
| Where it is recorded | Posted to an equity account such as Owner’s Draw, Owner Distribution, or Partner Draw; not an expense. | Recorded as Payroll Expense (and related payroll tax expense) on the books. |
| Tax deductible to the business? | No. Draws reduce owner equity and do not reduce taxable business income. | Yes. Wages paid to owner-employees are generally deductible business expenses. |
| Payroll tax required? | No payroll processing or withholding occurs when a draw is taken. | Yes. Social Security, Medicare, federal and state payroll taxes apply where required. |
| W-2 required? | No W-2 is issued. | Yes. The owner receives a W-2 at year-end. |
| Who can use it? | Sole proprietors, partnerships, and many LLCs taxed as sole proprietorships or partnerships. | Owners working in S corporations and C corporations generally must be paid through payroll. |
| Self-employment tax impact | Business profit is generally subject to self-employment tax regardless of how much is drawn. | Salary is subject to payroll taxes. In an S corporation, distributions above a reasonable salary may not be subject to self-employment tax, subject to IRS rules. |
| Payment frequency | Flexible: can be taken whenever business cash flow permits. | Typically follows a regular payroll schedule (weekly, biweekly, semi-monthly, or monthly). |
Comparison compiled from the research sources listed in Further Reading & Official Resources.
How to Record Owner’s Draw in QuickBooks
Here’s the practical, step-by-step setup for recording draws correctly.
Setting Up Owner’s Equity Accounts
In your Chart of Accounts, you want an Equity-type parent account (often simply called “Owner’s Equity”), with subaccounts beneath it for clarity.
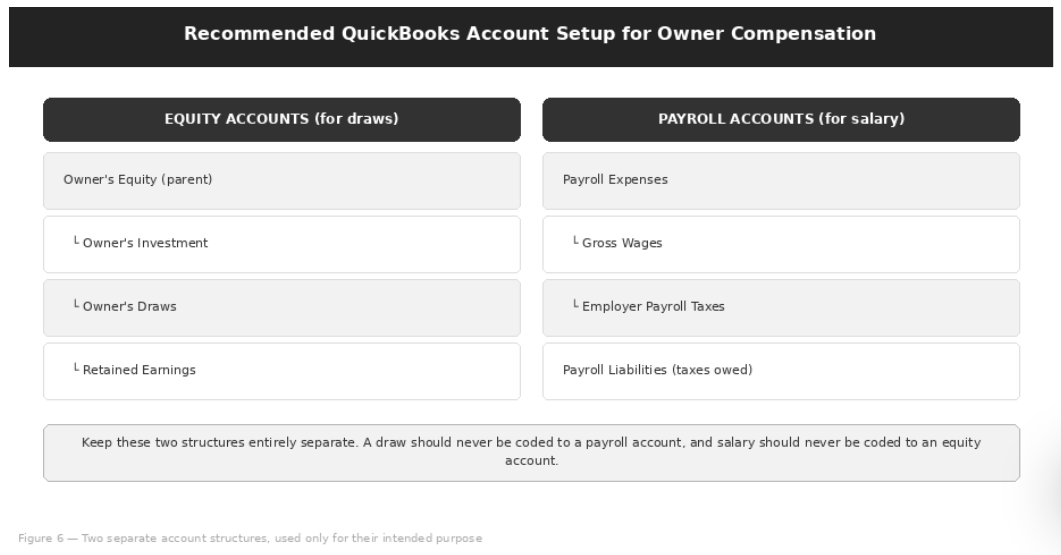
Two separate account structures, used only for their intended purpose
Creating Owner’s Draw Accounts
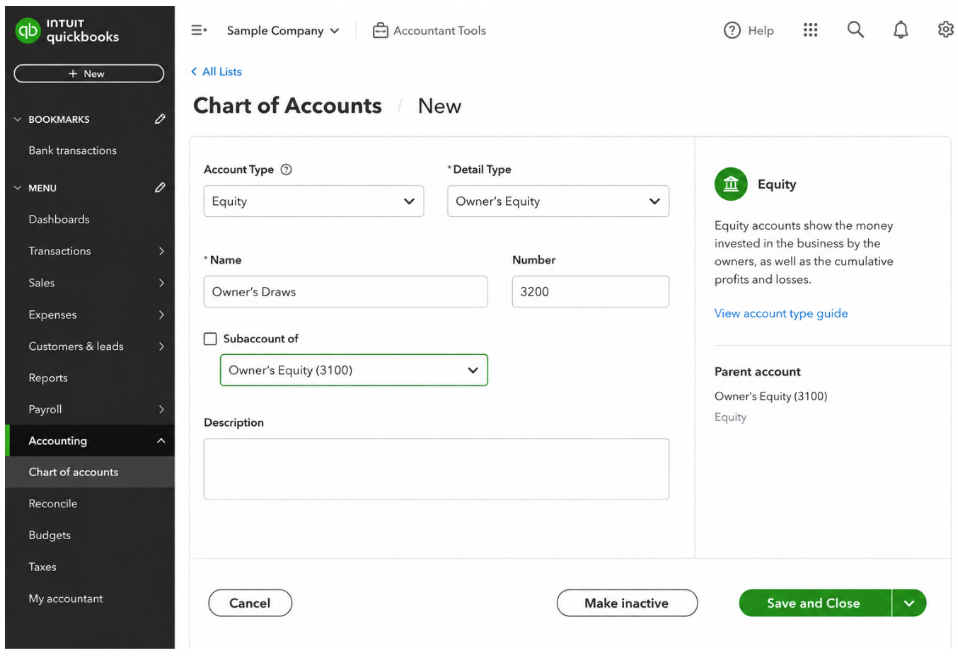
Accounting → Chart of Accounts → New: an Equity account named Owner’s Draws, set up beneath Owner’s Equity
Recording Withdrawals Correctly
When you transfer money from the business account to your personal account, record it as a transfer (or a check/expense, depending on your QBO setup) where the “category” or account selected is your Owner’s Draws equity account, never an expense account.
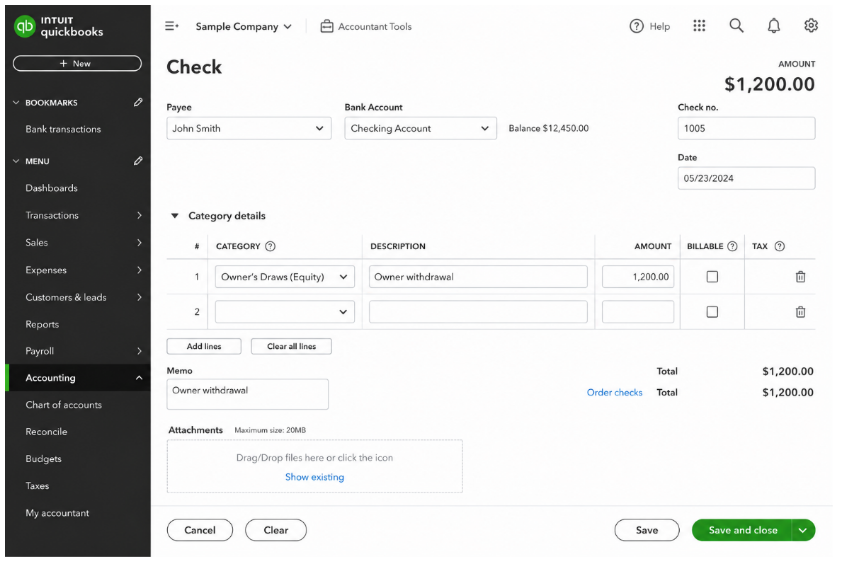
When recording a withdrawal, choose your Owner’s Draws equity account in the Category field. This ensures the transaction reduces equity rather than appearing as a business expense.
Handling Personal Expenses Paid from Business Funds
If you pay a personal expense directly from the business account (rather than transferring cash first), record the transaction the same way, categorized to Owner’s Draws, not to a business expense account. The amount paid is, in effect, a draw used to cover a personal cost.
Tracking Multiple Owners’ Draws
For partnerships or multi-member LLCs, maintaining separate draw subaccounts per owner is essential. Without this, you lose the ability to verify that each partner’s distributions match their ownership percentage and the partnership agreement.
Reconciling Draw Transactions
At least monthly, review the Owner’s Draws account(s) to confirm every transaction is correctly categorized and that the running total makes sense relative to what you know was actually withdrawn during the period.
Key Rule
A draw is always categorized to an Owner’s Draws equity account, whether it is a transfer to your personal account or a personal bill paid from the business account. It is never coded to an expense account.
Example Entries for Sole Proprietors and LLC Members
| Scenario | Debit | Credit |
|---|---|---|
| Sole proprietor transfers $2,000 to personal checking | Owner’s Draws (equity) $2,000 | Business Checking $2,000 |
| LLC member pays a personal credit card bill from the business account | Owner’s Draws, [Member Name] $850 | Business Checking $850 |
| Partner receives a $5,000 distribution per the partnership agreement | Partner’s Draws, [Partner Name] $5,000 | Business Checking $5,000 |
How to Record Salary in QuickBooks
If your entity type requires (or allows) salary (S corps, C corps, and any business with employees), here’s how to set it up correctly.
Setting Up Payroll Accounts
Your Chart of Accounts should include a Payroll Expenses account (or a small group of subaccounts: Gross Wages, Employer Payroll Taxes) and a Payroll Liabilities account for taxes withheld but not yet remitted.
Using QuickBooks Payroll
QuickBooks Online Payroll (or a comparable integrated payroll service) automates most of this correctly. It calculates withholding, generates pay stubs, handles tax remittance, and creates the necessary journal entries automatically. For an owner taking salary, you set them up in the payroll module exactly as you would any other employee, including their reasonable compensation amount for S corp owners.
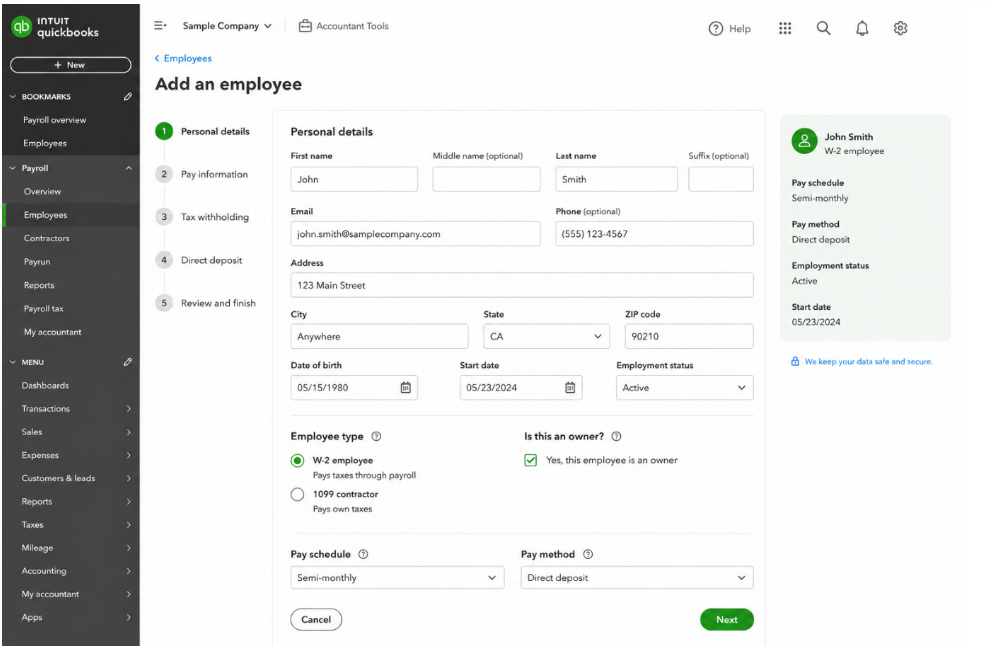
Payroll → Employees → Add Employee. The owner is set up the same way as any other staff member, with their salary, tax withholding elections, and pay schedule.
Recording Wages and Payroll Taxes
Each pay run, QuickBooks Payroll automatically records gross wages to your Payroll Expense account, the employer’s share of taxes to the same or a related expense account, and the withheld amounts to your Payroll Liabilities account until they’re remitted to the tax authorities.
Where Each Pay Run Is Recorded
Employer Payroll Obligations
Beyond withholding from the employee’s pay, the employer owes its own matching share of Social Security and Medicare, plus federal and state unemployment taxes. These are real costs the business incurs that don’t come out of the employee’s paycheck. They’re a separate expense layered on top of gross wages.
Creating Payroll Journal Entries
If you’re not using an integrated payroll service and need to record payroll manually (less common, but it happens), a basic entry splits the payment into gross wages (expense), withheld taxes (liability, until paid), and net pay (the actual cash that left the bank account).
| Account | Debit | Credit |
|---|---|---|
| Payroll Expense | Gross wages | |
| Payroll Liabilities (various) | Withheld taxes | |
| Cash / Business Checking | Net amount paid out |
Accounting → Journal Entry. Debit Payroll Expense for gross wages, credit various Payroll Liability accounts for withheld taxes, and credit Cash for the net amount paid out.
Handling Benefits and Withholdings
If the owner (or any employee) receives benefits, such as health insurance or retirement contributions, these typically have their own expense and/or liability accounts and specific tax treatment. Health insurance premiums for S corp owners, in particular, have a specific IRS treatment that should be set up correctly in payroll (often added to W-2 wages for tax purposes while remaining non-taxable for FICA).
Important Note
Health insurance premiums for S corp owners are often added to W-2 wages for income tax purposes while remaining non-taxable for FICA. Confirm the setup with your CPA before the first pay run of the year.
Example Transactions for S Corporations and C Corporations
| Scenario | QuickBooks treatment |
|---|---|
| S corp owner takes a $6,000/month reasonable salary | Run through Payroll: Gross Wages expense, payroll tax withholding, net pay to owner. |
| Same S corp owner also takes a $3,000 distribution that month | Recorded separately to a Shareholder Distributions equity account, not payroll. |
| C corp owner takes salary plus an annual dividend | Salary through Payroll as above; dividend recorded to a Dividends Paid equity account, taxed differently on the owner’s personal return. |
Consequences of Incorrect Classification
It’s worth being direct about what’s actually at stake when draws and salary get mixed up in the books.
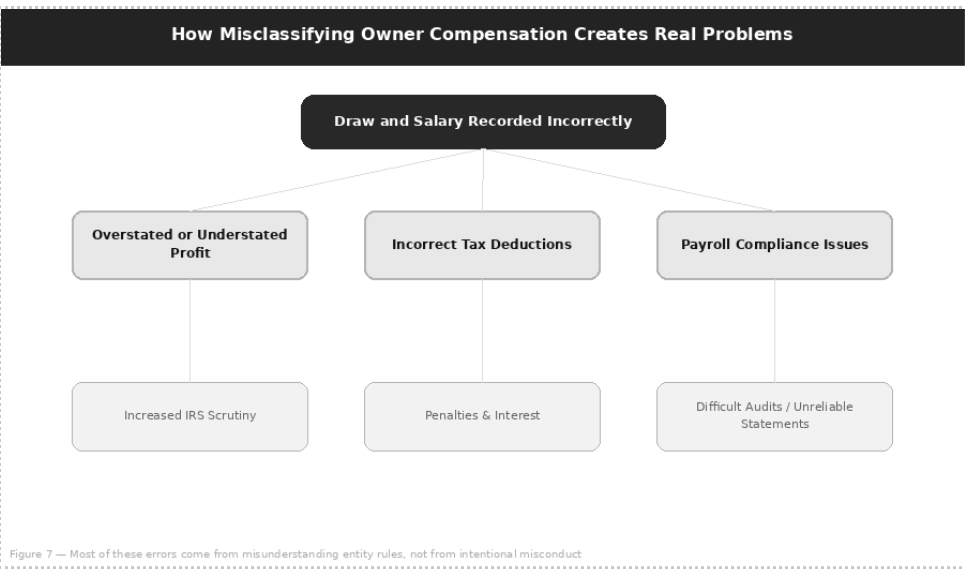
Most of these errors come from misunderstanding entity rules, not from intentional misconduct
| Consequence | What it means for your business |
|---|---|
| Overstated or understated profits | Misclassification directly distorts your reported profit, which affects everything from tax liability to how the business looks to a lender. |
| Incorrect tax deductions | Claiming a draw as a deductible expense (or failing to deduct legitimate salary) leads directly to an inaccurate tax return. |
| Payroll compliance issues | Missing W-2s, unfiled 941s, or unremitted payroll taxes are compliance failures independent of whether the underlying classification was an honest mistake. |
| Increased IRS scrutiny | S corp owners taking no salary or an unreasonably low one are specifically known to draw IRS attention; this isn’t a theoretical risk. |
| Penalties and interest | Unpaid or late payroll taxes accrue penalties and interest that compound over time, and reclassified compensation can trigger back taxes. |
| Complicated year-end accounting adjustments | Cleaning up a year’s worth of misclassified transactions at tax time is far more work (and more expensive) than classifying correctly throughout the year. |
| Problems during audits | Whether an IRS audit or financial due diligence for a loan or sale, inconsistent or incorrect compensation records raise immediate questions. |
| Difficulty producing reliable financial statements | If equity and expense accounts don’t reflect reality, none of your financial statements can be fully trusted. |
The Pattern Worth Remembering
Most errors covered in this guide stem from misunderstanding entity structure and accounting treatment, not from intentional misconduct. That’s actually good news: it means these problems are almost always fixable with the right understanding and a focused cleanup, which Section 11 covers in detail.
What Proper Owner Compensation Looks Like
Stepping back from the mechanics, here’s what a well-run compensation setup actually looks like in practice.
Maintaining Separate Business and Personal Finances
This is the foundation everything else is built on. A dedicated business bank account and credit card, used only for business transactions, makes every other step in this section dramatically easier.
Using Dedicated Equity Accounts
Separate, clearly labelled equity accounts for owner investment, draws, and retained earnings (per owner, if there’s more than one) give you a clean picture of each owner’s actual position in the business at any point in time.
Establishing Payroll When Required
If your entity type requires salary (S corp, C corp, or any business with non-owner employees), set up payroll properly from the start rather than treating it as an afterthought. A reliable payroll service handles the compliance side correctly and consistently.
Reviewing Compensation Regularly
For S corp owners in particular, reasonable compensation should be reviewed periodically, at least annually, to reflect changes in role, time commitment, business revenue, and industry benchmarks. What was reasonable three years ago may not be reasonable today.
Documenting Owner Withdrawals
Keep a simple record of draws taken, especially for businesses with multiple owners, so that distributions can be verified against ownership percentages and any partnership or operating agreement terms.
Coordinating Bookkeeping with Tax Planning
Your bookkeeper and your tax preparer (even if they’re the same person) should be aligned on how compensation is being handled throughout the year, not just at tax time. Surprises in March about how compensation was recorded all year are avoidable with a quick check-in periodically.
Maintaining Accurate Year-End Records
Before your books close for the year, confirm that all draws are properly recorded to equity, all salary has been run through payroll with W-2s prepared, and your equity accounts reconcile to what you expect. This is far easier to do in December than to reconstruct the following October.
Simple Self-Check
If someone asked you right now to explain exactly how much salary versus draws/distributions you’ve taken this year, and why that split is correct for your entity type, could you answer clearly? If not, that’s worth addressing before year-end.
Fixing Existing Mistakes and Knowing When to Get Help
If you’ve recognized any of the mistakes from Section 5 in your own books, here’s how to approach fixing them, and how to know when it’s time to bring in help.
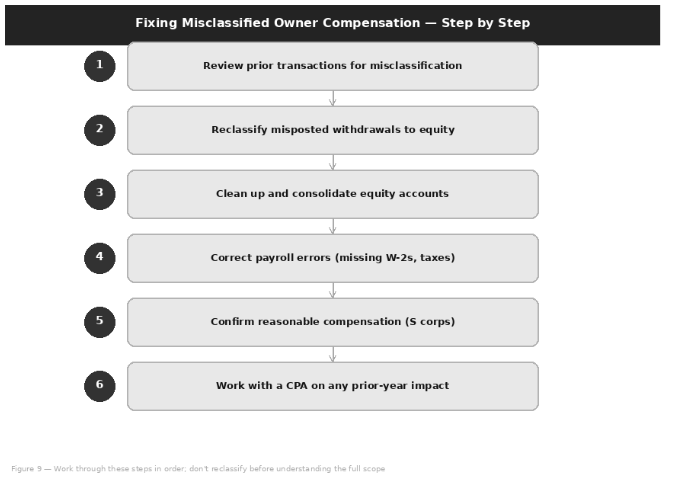
Work through these steps in order; don’t reclassify before understanding the full scope
Reviewing Prior Transactions
Start by exporting all transactions coded to equity accounts and to payroll/compensation expense accounts for the period you’re reviewing. Look specifically for anything that seems miscategorized based on what you now understand about draws versus salary.
Reclassifying Misposted Withdrawals
Transactions incorrectly coded as expenses that should have been draws can typically be reclassified directly in QuickBooks (or in bulk using the Reclassify Transactions tool if you have QuickBooks Online Accountant access).
Cleaning Up Equity Accounts
If draws and investments have been mixed together in a single generic equity account, separate them into properly labelled subaccounts going forward, and consider whether historical transactions are worth reclassifying for clarity (weighing the effort against the benefit).
Correcting Payroll Errors
Missing W-2s, unfiled 941s, or unremitted payroll taxes need to be corrected with payroll-specific processes. This often involves filing amended payroll returns and, in some cases, paying penalties that can sometimes be abated with reasonable cause. This is an area where professional help is particularly valuable, since payroll corrections have their own specific procedures and deadlines.
Working with a CPA or Bookkeeper
Especially where reasonable compensation, prior-year corrections, or payroll compliance are involved, a CPA’s involvement isn’t optional. Some of these corrections have direct tax return implications that shouldn’t be handled without their input.
Questions Owners Should Ask Before Changing Compensation Methods
- Does my current entity election actually allow the compensation method I’m using?
- If I’m an S corp, what would be considered reasonable compensation for my specific role and business?
- Will changing my compensation structure now affect anything already filed for this tax year?
- Do I need to set up or adjust payroll, and how quickly does that need to happen?
Signs That DIY Bookkeeping Is No Longer Sufficient
| Warning sign | Why it matters |
|---|---|
| You’re not fully confident in how your entity type is supposed to handle compensation. | Entity type decides whether draws, salary, or both apply. |
| You have multiple owners and distributions need to track precisely against ownership percentages. | Each owner’s draws must reconcile to the partnership or operating agreement. |
| You’ve never run a formal reasonable compensation analysis despite being an S corp. | Low or missing salary is a well-documented audit trigger. |
| Payroll has been missed, run incorrectly, or set up without professional guidance. | Payroll corrections have their own procedures and deadlines. |
| Tax season consistently involves your accountant asking questions about owner payments that take a while to sort out. | Unclear owner payments slow down and complicate every return. |
Building a Compensation System That Supports Business Growth
As a business grows (more owners, more revenue, possibly a change in entity election), the compensation structure needs to grow with it. A system that worked cleanly for a single-owner sole proprietorship may need real adjustment after an S corp election or the addition of a business partner. Building the habit of reviewing this periodically, rather than only at the point of a problem, is what separates businesses that handle this well from those that end up with a cleanup project.
Not Sure If Your Current Setup Is Right?
If you’d like a second opinion on how your owner compensation is being recorded, or want help setting up payroll and equity accounts correctly for your entity type, we’re happy to take a look. No obligation, just a clear answer about what you’re dealing with.
References
Frequently Asked Questions
An owner’s draw is a withdrawal of equity the owner already owns. It reduces equity on the Balance Sheet and is not a business expense. A salary is payment for work performed, recorded as a deductible Payroll Expense on the P&L, with payroll taxes withheld and a W-2 issued at year-end.
No. A sole proprietor can’t legally be their own W-2 employee, and a single-member LLC taxed as a disregarded entity follows the same rule. Both take owner’s draws, unless the LLC has elected to be taxed as an S corporation or C corporation.
No. A draw isn’t a cost the business incurred to generate revenue, so it can’t be deducted. It reduces owner equity and does not reduce taxable business income.
Not on the draw itself. You’re taxed on your share of the business’s profit for the year, whether you withdrew it or not. A sole proprietor who leaves $20,000 of profit in the business account still owes tax on that $20,000.
There is no fixed formula. The IRS expects an S corp owner’s salary to reflect what the business would have to pay someone else to do the same job, considering the owner’s role, time devoted, industry norms, and the business’s overall revenue.
Create an Equity account with the Detail Type Owner’s Equity and an “Owner’s Draws” subaccount. When you transfer money to your personal account or pay a personal expense, select the Owner’s Draws equity account as the category, never an expense account.
Set yourself up in QuickBooks Payroll (Payroll → Employees → Add Employee) exactly as you would any other employee, with your reasonable compensation amount, tax withholding elections, and pay schedule. Record any additional distributions separately to a Shareholder Distributions equity account.
Business expenses are overstated, profit is understated, and payroll tax obligations may be misrepresented. Reclassify the transactions to your Owner’s Draws equity account, and involve a CPA if prior-year returns or payroll filings are affected.
No. There’s no draw concept in a C corp. Working owners are employees paid salary through payroll, and profits reach shareholders through dividends, which are taxed differently on the owner’s personal return.
Summary
Key Takeaways
An owner’s draw is a withdrawal of equity you already own; a salary is payment for work performed. Which one applies is determined by your legal structure and tax election, not by preference.
A draw reduces equity on the Balance Sheet, never appears on the P&L, and is not tax-deductible. A salary is a deductible expense that triggers payroll tax withholding, Form 941 filings, and a W-2.
Sole proprietors and single-member LLCs taxed as disregarded entities take draws; partners and multi-member LLC members take distributions and may receive guaranteed payments.
In an S corporation, salary comes first: a working owner must be paid reasonable compensation through payroll before taking distributions. Distributions only is a known audit trigger.
C corporation owners are paid salary, dividends, or both. There is no draw concept in a C corp.
Draws are not a taxable event. The tax follows the profit, not the withdrawal, and self-employment tax of 15.3 percent applies to the net profit of a sole proprietorship, partner’s share, or LLC member’s share.
In QuickBooks, keep a dedicated Owner’s Draws equity subaccount (one per owner) and run salary through payroll. A draw is never coded to an expense account, and salary is never coded to equity.
Most misclassification is fixable: review before reclassifying, correct payroll errors with payroll-specific processes, and involve a CPA wherever prior-year returns or reasonable compensation are affected.
Final Thoughts
Conclusion: Getting Paid the Right Way
The difference between an owner’s draw and a salary isn’t a technicality. It’s determined by your entity type, it has direct tax consequences, and getting it wrong creates problems that compound the longer they go unaddressed. The good news is that once you understand which rules apply to your specific structure, recording compensation correctly in QuickBooks is straightforward: dedicated equity accounts for draws, proper payroll setup for salary, and a habit of reviewing the split periodically.
If you’ve found gaps in how your own compensation has been recorded while reading this guide, that’s a completely normal place to be, and it’s fixable. The sooner it’s addressed, the simpler the fix tends to be.
Resources